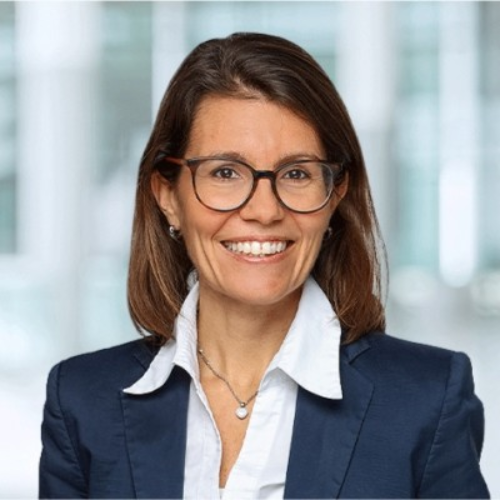


In an exclusive interview with Mayur Joshi of RegTechTimes, Anne-Sophie Gógl, Chairwoman of the Digital Euro Association, discusses the evolving European debate around CBDCs (central bank digital currencies), stablecoins and tokenised money.
Drawing on her involvement in discussions around digital currencies since 2020, Gógl explains how Europe’s priorities have shifted towards strategic autonomy, financial infrastructure and reducing dependence on non-European payment providers. She also discusses the regulatory challenges surrounding the digital euro, the importance of interoperability, privacy and AML (anti-money laundering) compliance, and the role of banks and payment service providers in implementing new forms of digital money.
The conversation examines how Europe can build a competitive and interconnected digital financial ecosystem while maintaining financial stability, protecting consumers and ensuring trust in an increasingly technology-driven monetary system.
How has Europe’s debate around digital currencies changed since 2020?
Question: You have been closely involved in the European debate around CBDCs and digital money since 2020. How has the conversation around digital currencies changed, and what do you believe are the most important questions Europe needs to answer now?
Anne-Sophie Gógl: When I first became involved in the debate around digital currencies in 2020, the world looked very different.
At the time, Facebook’s Libra project, later renamed Diem, had raised fundamental questions in Europe about the future of money and the role of private technology companies in the monetary system. There was also concern that people might increasingly use privately issued stablecoins instead of cash for everyday payments, gradually weakening the role of central bank money as the monetary anchor. Both the early discussions around the digital euro and the development of MiCA were shaped, in part, by the need to respond to global stablecoin initiatives.
Since then, however, the geopolitical environment has changed significantly, and so has Europe’s perspective on digital money.
Today, the debate is no longer primarily about responding to individual private initiatives. It has become a much broader discussion about Europe’s strategic autonomy, its dependence on non-European payment providers, and its ability to shape its own financial infrastructure.
This is an important shift in perspective. Rather than defining Europe’s ambitions in response to developments elsewhere, we are increasingly asking what kind of monetary and payment ecosystem Europe wants to build for itself.
At the same time, the discussion has moved beyond the digital euro alone. Regulated stablecoins, tokenised commercial bank money and wholesale central bank money are becoming important parts of the broader picture.
For me, the most important questions now are how we can bring these different forms of digital money together, ensure interoperability, and translate Europe’s regulatory foundations into competitive solutions that deliver real value for citizens and businesses.
Ultimately, the ambition should not simply be to reduce dependencies, but to build a resilient, innovative and competitive European financial ecosystem on our own terms.
How can the digital euro, stablecoins and tokenised bank deposits coexist?
Question: The digital euro is being developed within an increasingly complex regulatory and financial ecosystem that also includes stablecoins and tokenised bank deposits. How should policymakers ensure that these different forms of digital money can coexist without creating unnecessary regulatory fragmentation?
Anne-Sophie Gógl: I believe we need to move away from the idea that there will be one winning form of digital money.
Central bank digital currencies, regulated stablecoins and tokenised commercial bank money have different characteristics and can serve different purposes. They should not automatically be viewed as competing solutions.
Central bank money remains the anchor of the monetary system. Commercial bank money continues to play a fundamental role in financing the economy, while regulated stablecoins can introduce new capabilities, particularly for cross-border transactions and digital markets.
From a regulatory perspective, the challenge is to ensure consistent safeguards without treating fundamentally different instruments as though they were identical.
The principle should be same risks, same regulatory outcomes, while recognising differences in legal claims, issuance structures and underlying business models.
Equally important is interoperability. If each form of digital money operates within its own closed ecosystem, we risk reproducing fragmentation in a new technological environment.
At the Digital Euro Association, we advocate a broader ecosystem perspective precisely because each form of regulated digital money has its own legitimate role. They address different user groups and use cases. The objective should not be to promote one form of money at the expense of another, but to enable them to coexist within a stable, interconnected monetary system.
Ultimately, the question is not which form of digital money will dominate, but how they can work together.
What are the biggest challenges in moving the digital euro towards large-scale adoption?
Question: From a regulatory perspective, what are the biggest challenges in moving the digital euro from a policy concept and pilot environment toward potential large-scale adoption?
Anne-Sophie Gógl: I see three major challenges: legal certainty, operational implementation and, above all, market adoption. While the first two are essential prerequisites, adoption will ultimately be the decisive test for the digital euro.
The first is establishing a regulatory framework that balances public policy objectives with practical market realities. Questions around legal tender, privacy, holding limits, distribution obligations and the compensation of payment service providers are not merely technical details. They determine whether the digital euro can function effectively within the existing financial system.
The second challenge is implementation. Banks and payment service providers will have to integrate the digital euro into existing payment systems, customer interfaces, compliance processes and operational infrastructures. This requires considerable coordination, investment and sufficient implementation time.
A payment instrument can be technically excellent and legally robust, but it will only succeed if consumers and merchants see a genuine benefit in using it. That is why adoption must be considered from the outset, not only after the infrastructure has been built.
For consumers, the value proposition could include a digital means of payment designed for broad acceptance across the euro area, strong privacy protections and offline functionality. For merchants, transaction costs and ease of acceptance matter; for payment service providers, a fair compensation model and manageable implementation costs are essential.
The European Parliament and the Council are negotiating the legislative framework on the basis of the European Commission’s proposal, with the Commission also participating in the trilogue process. Meanwhile, the Eurosystem is preparing a pilot scheduled for the second half of 2027. Importantly, a decision to issue the digital euro has not yet been taken.
The real measure of success will not be whether Europe can introduce a digital euro, but whether it can create one that delivers tangible value and becomes part of everyday payments.
How should responsibilities be divided across the digital euro ecosystem?
Question: The digital euro will involve central banks, commercial banks, payment service providers and technology companies. How should responsibilities for compliance, consumer protection, data governance and operational resilience be divided across this ecosystem?
Anne-Sophie Gógl: The digital euro is being designed within Europe’s existing two-tier monetary system, and I believe that distinction is important.
The Eurosystem would issue the digital euro and provide the core infrastructure. Banks and other payment service providers would remain the primary interface for consumers and businesses, as they already are today, responsible for customer relationships, onboarding, payment services and applicable compliance obligations.
This builds on existing institutional responsibilities rather than creating an entirely new relationship between central banks and citizens.
However, clear accountability is essential. When several institutions contribute to a payment, responsibilities for cybersecurity, fraud prevention, customer complaints, operational incidents and data protection cannot become fragmented.
Technology providers will also play an important role, but outsourcing technical functions must not dilute regulatory accountability.
I would therefore emphasise the need for common operational standards, clearly defined responsibilities and robust coordination mechanisms across the ecosystem.
This is particularly important for operational resilience. Consumers do not distinguish between a problem at their bank, a technology provider or the underlying payment infrastructure. They simply expect their payment to work.
Ultimately, trust in the digital euro will depend on the resilience of the entire ecosystem, not just the reliability of its central infrastructure.
How can the digital euro balance privacy with AML compliance?
Question: Privacy has been one of the most important public concerns surrounding the digital euro. What balance should be struck between privacy, financial crime prevention and regulatory requirements such as AML and transaction monitoring?
Anne-Sophie Gógl: Privacy is not a secondary feature of the digital euro. It is fundamental to public trust and, in my view, one of the project’s most important potential differentiators.
We should start by recognising that privacy and financial crime prevention are both legitimate public interests. The challenge is to design a system that protects both without assuming that greater surveillance automatically produces greater security.
The current digital euro design makes an important distinction between online and offline payments.
For online transactions, payment service providers would retain access to the information necessary to fulfil their legal obligations, including anti-money laundering and fraud prevention. The Eurosystem itself would not be able to directly identify individuals from their payments.
Offline payments would offer a higher degree of privacy, closer to cash. Individual transaction details would remain between the payer and the recipient, while controls would apply when funds enter or leave the offline wallet.
I consider this distinction particularly valuable because it recognises that different payment situations justify different levels of data access.
More broadly, we should be careful not to lose the privacy characteristics of public money as payments become increasingly digital.
The objective should be privacy by design, combined with proportionate and effective financial crime prevention. These goals are not mutually exclusive, but achieving them requires deliberate choices in both legislation and technology.
Where are the biggest opportunities and risks for regulated stablecoins?
Question: Stablecoins are developing rapidly alongside CBDCs, with frameworks such as MiCA bringing greater regulatory clarity in Europe. Where do you see the strongest opportunities for stablecoins, and where do you see the greatest regulatory or financial stability risks?
Anne-Sophie Gógl: I see particularly strong opportunities for regulated stablecoins where existing payment infrastructure creates friction: cross-border payments, global payouts, corporate treasury and settlement in tokenised markets. They can allow businesses to move value across borders, potentially faster and outside conventional banking hours.
Agentic payments are an especially interesting emerging use case. AI agents may increasingly purchase services automatically—for example, an API call, a dataset or computing power. Stablecoins can support such machine-to-machine and low-value transactions around the clock, though they are not the only possible payment solution.
For Europe, this makes competitiveness more urgent. MiCA provides a valuable regulatory foundation, but clear rules alone will not ensure that euro-denominated stablecoins or innovative applications can scale here.
In our response to the European Commission’s MiCA review, the Digital Euro Association emphasised effective and enforceable redemption rights, including for eligible holders using self-hosted wallets or cross-border arrangements, subject to appropriate identity, AML and sanctions checks.
We also advocated a more evidence-based, liquidity-focused approach to reserve requirements: fixed bank deposit allocations do not automatically ensure that an issuer can meet redemptions under stress. Properly safeguarded multi-issuance arrangements involving EU and non-EU entities should remain possible, with clear responsibilities and effective supervision.
The key risks include reserve liquidity shortfalls, failures in redemption arrangements, supervisory gaps and operational dependencies. Automated payments also require clear authorisation and compliance responsibilities.
Europe should combine strong safeguards for holders and financial stability with the room to develop competitive, trusted euro-denominated payment solutions.
What regulatory frameworks are needed for tokenised bank deposits?
Question: Tokenised bank deposits and other forms of tokenised money could significantly change how payments and financial transactions work. What regulatory and governance frameworks will be needed to ensure that innovation in tokenised money develops safely?
Anne-Sophie Gógl: Tokenised bank deposits can bring existing banking relationships into new technological environments without changing the basic role of commercial bank money in our two-tier monetary system.
Rather than creating a new regulatory regime for every technological development, we should build on existing financial regulation and ensure it remains effective in tokenised environments. Clear responsibilities and practical cooperation between banks, central banks and infrastructure providers will be essential.
What lessons can emerge from the digital euro’s practical development phase?
Question: The digital euro pilot is bringing banks and payment service providers into the practical development of how a CBDC could work in areas such as person-to-person payments, point-of-sale transactions and e-commerce. What are the most important lessons emerging from this practical phase?
Anne-Sophie Gógl: I think it is important to distinguish between what the pilot is intended to demonstrate and what we can already conclude.
The operational pilot is scheduled to begin in the second half of 2027. The current phase focuses on development and integration, with 36 selected payment service providers preparing to participate.
This includes connecting to the digital euro service platform, developing payment services, conducting technical testing and preparing the customer-facing experience.
We therefore should not claim that the pilot has already demonstrated consumer adoption or operational scalability.
Nevertheless, the preparation itself highlights an important lesson: the digital euro is not simply a central bank technology project. It is an ecosystem implementation project.
Its success depends on how effectively banks, payment service providers, merchants and the Eurosystem can work together.
I would pay particular attention to three aspects as the pilot progresses.
First, integration complexity: how easily can different payment providers connect the digital euro to their existing infrastructure?
Second, user experience: can consumers and merchants use the digital euro as intuitively as the payment instruments they already know?
Third, operational resilience: can the infrastructure function reliably across different payment environments and under adverse conditions?
In my view, these practical findings will be at least as important as the technical performance of the underlying infrastructure.
The pilot provides an opportunity to identify implementation challenges early, rather than discovering them only during a potential large-scale rollout.
What new compliance and financial crime risks could emerge as digital money evolves?
Question: As digital money becomes more programmable, interconnected and technology-driven, what new compliance and financial crime risks should banks, payment providers and regulators be preparing for today?
Anne-Sophie Gógl: As payments become more automated and interconnected, institutions will need to make sure that responsibility for compliance and oversight remains clear, including when transactions involve several providers or platforms.
The digital euro itself is not intended to be programmable money. There is an important distinction between restricting how money may be used and enabling conditional or automated payments.
I would focus on building appropriate controls and accountability into new payment processes from the outset, while ensuring that regulation remains proportionate and technology-neutral.
What will Europe’s digital money landscape look like by 2031?
Question: Looking ahead five years, what do you expect Europe’s digital money landscape to look like, and what should financial institutions and regulators be doing now to make sure innovation, financial stability and trust develop together?
Anne-Sophie Gógl: Looking towards 2031, I expect Europe’s monetary landscape to be considerably more diverse, but also more interconnected.
I do not expect one form of digital money to replace all others.
Instead, I see a future in which central bank money, commercial bank money and regulated stablecoins continue to coexist, while the infrastructures through which they move become increasingly digital and interoperable.
The digital euro could become an additional public payment option for citizens and businesses, complementing cash and private payment solutions. At the same time, tokenised deposits and regulated stablecoins could play increasingly important roles in wholesale markets, corporate treasury and cross-border transactions.
What will determine Europe’s success is not simply whether these instruments exist, but whether they operate within a coherent and competitive financial ecosystem.
For financial institutions, my message would be to engage early. Digital money should no longer be treated exclusively as an innovation or regulatory project. It is becoming a strategic question about future infrastructure, customer relationships and business models.
For regulators, the priority should be to provide legal certainty, preserve financial stability and support interoperability without unnecessarily restricting innovation.
And for Europe as a whole, I believe we need to be more ambitious.
Europe has an opportunity to shape the next generation of monetary infrastructure according to its own values: stability, privacy, openness and competition.
Looking ahead, I believe we will see a fundamental transformation of financial market infrastructure. As both money and financial assets become increasingly tokenised, the challenge will be to build an infrastructure that brings them together and enables transactions to be executed and settled seamlessly.
Europe’s success will not be measured by the number of digital currencies or platforms we develop, but by whether we create a financial ecosystem that is trusted, competitive and delivers real value to businesses and society.
Key takeaways from Anne-Sophie Gógl’s interview
- Europe’s digital money priorities are changing: The debate has expanded from responding to private digital currency initiatives to addressing strategic autonomy and dependence on non-European payment providers.
- Different forms of digital money can coexist: CBDCs, regulated stablecoins and tokenised commercial bank money have different characteristics and use cases. Interoperability is essential to prevent fragmentation.
- Adoption will determine the digital euro’s success: Legal certainty and operational readiness are important, but consumers, merchants and payment providers must see practical value in using it.
- Privacy and financial crime prevention must work together: Privacy by design and proportionate AML controls can support both public trust and effective financial crime prevention.
- Stablecoins offer opportunities alongside risks: Cross-border payments, corporate treasury, tokenised markets and automated payments are potential use cases, while reserve liquidity, redemption rights and supervisory gaps remain important concerns.
- Clear accountability is essential: Banks, payment service providers, central banks and technology companies need defined responsibilities for compliance, cybersecurity, data protection and operational resilience.
- The digital euro is not intended to be programmable money: A distinction must be maintained between restricting how money can be used and enabling conditional or automated payments.
- Europe’s future depends on an interconnected financial ecosystem: Legal certainty, financial stability, privacy, competition and interoperability will shape how digital money develops over the coming years.